News
Stuck Between Bank and VC: Why Mid-Sized Real Estate Issuers Can't Get Funded, Based on a 250-Issuer Cohort Analysis
Why can't mid-sized European real estate get funded? A 250-issuer cohort analysis of the financing gap and the digital securities path out
Kristina Stark
Junior Growth Manager
last updated on

Share
On this page
Contact Us
ONINO provides infrastructure for digital & tokenized financing to make your next financing a success.
Quick Takeaway
Mid-sized European real estate deals in the €2M to €20M band fall into a structural financing gap: too small for institutional funds (which target €25M+ tickets and 15-20% IRR) and too capital-costly for banks under Basel III/IV. Across a 250-issuer cohort, more than two-thirds of mid-market deals reviewed ended up repriced down, restructured into a larger combined deal, or shelved entirely, despite sound underwriting. Based on ONINO's analysis of 250 issuer conversations, 2024 to 2026. Digital securities infrastructure is a third path that addresses both sides of the gap: issuers raise from 50-500 investors under EU prospectus exemptions, and digital issuance makes small tickets economical to administer, with the minimum set by the issuer, which opens the asset class to a far wider investor base.
The mid-market real estate financing gap in Europe has a defined shape. It is not a vague complaint about "tight credit markets." It is a structural band - roughly €2M to €20M in total deal size - where two well-developed funding paths exist on either side, and neither covers the middle.
Below €2M, a developer or asset manager can usually finance through Sparkasse, Volksbank, or local bank credit, often layered with personal guarantees or family equity. Above €20M, institutional debt funds, life-insurance balance sheets, and large-ticket private equity become viable counterparties. In between sits the operational core of European real estate: residential value-add projects, mixed-use redevelopment, hotel and serviced-apartment financing, smaller commercial assets, and energy-efficient retrofits that require capex stacks not standard mortgages.
Why banks pass
The bank-side answer is rarely "your deal is bad." It is more often a stack of capital-cost, regulatory, and operational reasons that combine to make a mid-sized real estate deal uneconomic for the lender's balance sheet.
Capital cost under Basel III / IV. Real estate exposure carries a specific capital weighting that, for non-prime collateral or higher-LTV positions, can push the required regulatory capital well above what the deal's interest margin will return. For a €5M deal at standard mid-market spreads, the after-capital return often does not clear the bank's internal hurdle.
LTV ceilings that mid-market deals routinely brush. Banks underwrite to conservative LTVs on residential and mixed-use collateral. A value-add deal that requires 65-75% leverage to make sponsor economics work is structurally outside many banks' standard sheet - even when the underlying NOI projections are sound.
Reduced SME credit appetite since 2022. Across the cohort, post-2022 credit committees applied notably tighter review standards to mid-sized real estate exposures, particularly residential development. This is consistent with broader ECB lending data showing tightening in real estate exposure across the eurozone.
The unit economics of relationship lending. A €5M deal carries the same legal, KYC, and credit-committee cost as a €50M deal - but generates a tenth of the fee revenue. For all but the most relationship-driven local banks, the deal simply does not pay back the diligence overhead.
The deal can be sound. The structural answer is still no.
Why VC and PE pass
Venture capital does not finance real estate at all. The asset class returns 6-12% over multi-year holds, while VC mandates target 25%+ IRR on companies that can theoretically return 10-100×. Real estate's risk-return profile is the structural opposite of VC's. This is not a fixable mismatch - it is a definitional one.
Private equity and institutional real estate funds do finance the asset class, but they pass on the €2M-€20M band for different structural reasons:
Return profile mismatch. Most institutional real estate funds target 15-20% IRR on value-add strategies or 8-12% on core-plus. Mid-market deals can produce these returns at the asset level, but the cost of running a small deal through an institutional vehicle - legal, due diligence, ongoing asset management - erodes net IRR to where the fund's underwriting hurdle no longer clears.
Ticket-size economics. A €100M closed-end fund deploying into 6-10 deals does not look at €5M positions. The diligence cost is the same as a €50M position; the fund's allocation strategy doesn't accommodate the small ticket; the GP's economics push toward larger deals.
Timeline mismatch. Mid-market deals often need committed capital in 4-8 weeks to compete on the sell side. Institutional fund processes - IC approval, fund-of-fund LP look-through, legal subscription docs - typically run 8-16 weeks for new commitments. By the time the institutional process closes, the deal has moved.
Mandate fit. Institutional capital concentrates in prime commercial, large residential portfolios, and core logistics. A €5M residential value-add deal in a tier-2 German city is operationally interesting but mandates-out for most institutional vehicles.
The deal can be sound. The structural answer is still no.
The cost of the gap
The financing gap has direct, quantifiable cost - to issuers, to investors, and to the broader real estate economy.
To issuers. Across the cohort, projects in the gap typically end in one of three places: they get repriced at a worse valuation (developer absorbs a 10-20% haircut to fit a bank's smaller LTV envelope); they get restructured into a larger combined deal that takes 6-12 months to assemble; or they get shelved entirely. Each outcome carries opportunity cost - delayed delivery, lost market window, eroded sponsor returns.
To investors. The gap simultaneously cuts off retail and affluent investors from the asset class. Mid-market real estate has historically produced more risk-adjusted return than core commercial precisely because the institutional crowd does not touch it. Closing the supply-side of the gap (issuer-side) without addressing the demand-side (investor-side) only relocates the problem.
To housing and urban supply. Residential redevelopment, value-add, and energy-efficient retrofits - exactly the asset profile that sits in the gap - is also exactly the asset profile European policy frameworks need more of. The gap is a real-economy bottleneck, not just a financial-markets curiosity.
If this pattern describes a deal you're trying to fund, the structural issue is rarely the deal - it's the path. See how mid-sized real estate raises are structured through digital securities infrastructure.
How digital securities infrastructure changes the funding calculus
The structural exit from the gap is not "find a more flexible bank" or "pitch a different fund." Both paths have rational reasons to pass - those reasons are not going to change. The exit is a third path: digital securities infrastructure that connects mid-sized issuers directly to a wider investor base, under a regulated framework that institutional capital and retail capital can both recognize.
Prospectus exemptions and multi-investor structures (supply side)
EU regulation already allows mid-sized real estate raises without a full prospectus, but only if the structure fits inside specific exemption thresholds. Three regimes matter:
EU Prospectus Regulation exemption for small offers: up to EUR 12 million per issuer over 12 months (Art. 3(2) PR as amended by the Listing Act); in Germany with a securities information sheet (WIB) approved for publication by BaFin, Germany only, no passport.
ECSPR (European Crowdfunding Service Provider Regulation): raises up to €5M per project owner over 12 months through a licensed crowdfunding service provider, passportable.
eWpG (Gesetz über elektronische Wertpapiere) in Germany - provides a regulated framework for electronic securities, including bearer bonds (Inhaberschuldverschreibungen), recorded in a register kept by a BaFin-authorised registrar.
A mid-sized real estate issuer can structure a raise of up to EUR 12 million inside these exemptions in Germany, or up to EUR 5 million EU-wide through a licensed crowdfunding service provider. The technology layer is incidental. The regulatory layer is what makes the raise legal, recognized, and operationally manageable.
The second piece is multi-investor structures. Managing 50 investors through manual spreadsheets, KYC PDFs, and email confirmations breaks down operationally somewhere around 30-40 participants. Managing 200 or 500 is impossible without infrastructure. Digital securities platforms automate the cap table, the distribution payments, the reporting, the secondary transfers, and the regulatory record-keeping - bringing the per-investor operational cost down to where a €500-€5,000 ticket is economically viable for the issuer.
Opening up for more investors
The supply-side fix is meaningless without a demand-side fix. If issuers can raise from many investors but investors can't enter at deal-relevant ticket sizes, the gap stays open. The minimum-ticket shift is the single most visible structural change tokenization delivers:
Digital issuance makes small tickets economical to administer; issuers commonly set minimums in the low thousands, and the minimum remains the issuer's decision.
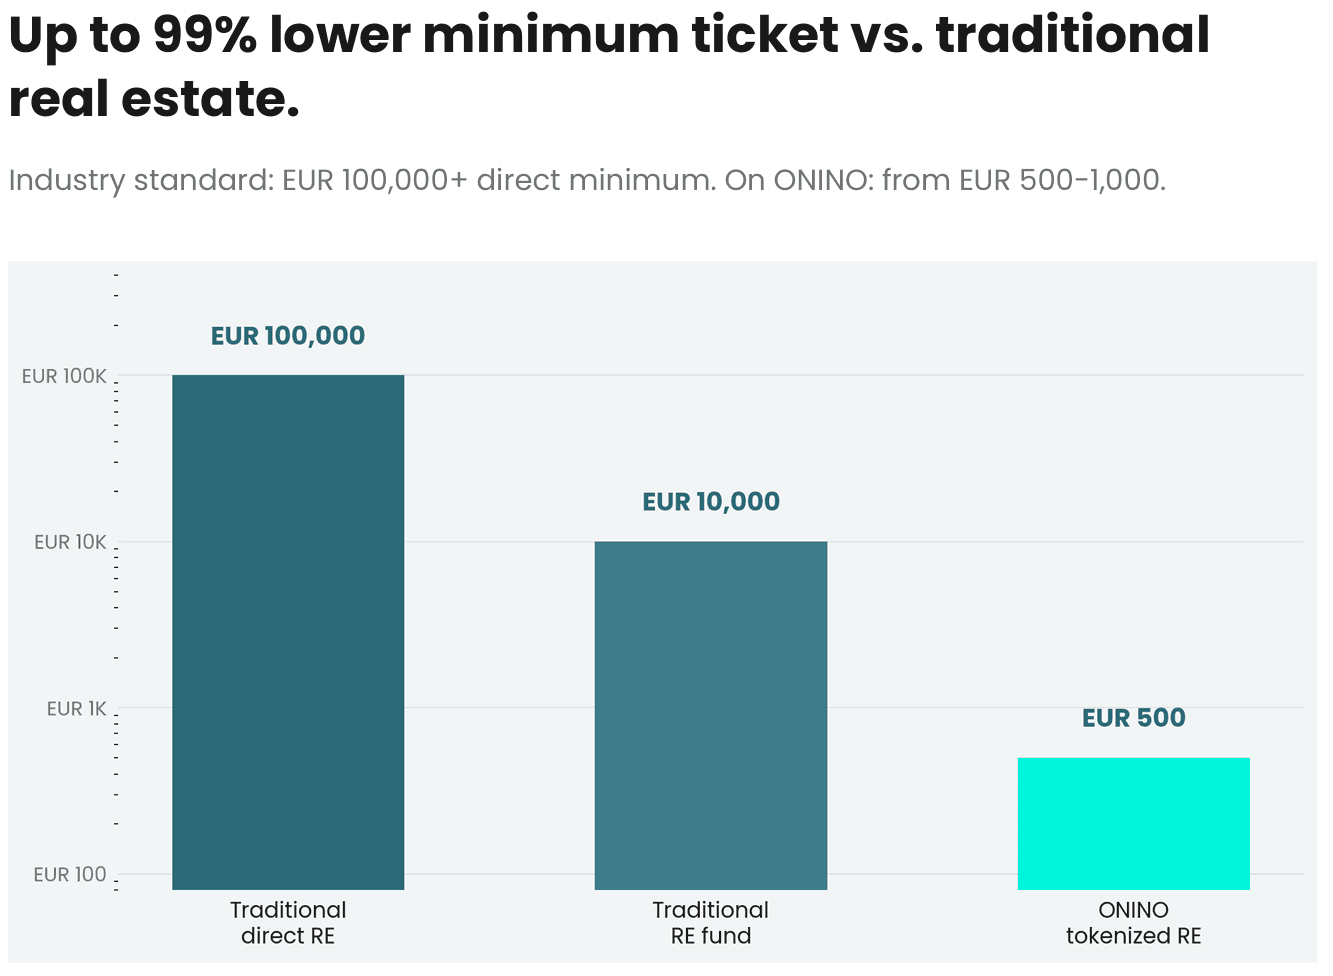
Traditional direct real estate co-investment has effectively excluded everyone outside ultra-high-net-worth and institutional family offices. A €100,000 minimum ticket prices out the affluent private investor, the smaller family office, and any pooled member structure. Traditional real estate funds improved access by an order of magnitude to roughly €10,000 - but still gate the long tail of affluent investors and operationally make small allocations expensive.
Tokenized real estate on regulated digital securities infrastructure makes small tickets economical to administer, and the minimum remains the issuer's decision. That is a function of how the on-chain cap-table layer eliminates the per-investor fixed cost that traditional fund structures inherit from transfer agents, fund admin, and paper-based subscription docs. When fixed cost per investor drops from hundreds of euros to single digits, the floor of a viable allocation drops with it.
This is where ONINO converts the gap into a solution. ONINO supplies the issuance software with pre-integrated registrar and custody partners: eWpG electronic securities, integrated KYC/AML at onboarding and ERC-3643 as the on-chain compliance standard. The crypto securities register is maintained by a BaFin-authorised registrar; the permission sits with that partner, not with ONINO. The issuer gets a path to a wider investor base at deal-relevant size. The investor gets access to mid-market real estate at a ticket they can actually allocate. The asset manager or financing consultant structuring the deal gets to deploy a white-label digital securities platform under their own brand, with the licensed functions running through pre-integrated partners.
The structural gap closes from both sides at once. That is what makes digital securities the structural exit - not just a different path.
Why digital securities are not crypto
The most common misread among issuers evaluating this path for the first time: assuming "tokenization" means "crypto." It does not. Digital securities are regulated financial instruments under MiFID II. They have a named issuer, contractually defined rights (interest, principal, dividend, participation), an EU regulatory framework (eWpG in Germany, ECSPR cross-border, AIFMD for fund structures), and registry-grade record-keeping by supervised entities such as BaFin-authorised registrars. MiCA - the EU's crypto-asset regulation - explicitly excludes financial instruments already covered by MiFID II. Digital securities sit in the MiFID II perimeter, not the MiCA one. This is the regulatory point that asset managers, banks, and family offices need clear before they will move forward.
Which funding path fits which deal?
The decision matrix below maps the three structural paths against six criteria that determine fit. Use it to identify which path a specific deal belongs in - and where digital securities is the only structurally available option.
Criterion | Bank lending | PE / institutional fund | Digital securities |
|---|---|---|---|
Deal size sweet spot | €10M+ on standard LTV terms | €25M+ ticket per position | €1M-€50M |
Return profile fit | Fixed coupon, 4-8% | 15-20%+ IRR on value-add | Variable, 6-15% blended |
Timeline to close | 4-12 weeks | 6-18 months (IC + LP look-through) | 4-8 weeks post-platform setup |
Investor count | 1 (the lender) | 1-3 LPs | 50-500 retail and affluent investors |
Regulatory path | Bank credit committee | Fund prospectus or AIFMD | EU Prospectus exemption, ECSPR, or eWpG |
Liquidity for investor | None (lender holds to maturity) | 7-10 year fund lockup | Transferable on the register; liquidity depends on buyers |
A second table makes the gap itself visible - the deal profile that gets systematically excluded from the first two columns:
Deal attribute | Why banks pass | Why PE / institutional funds pass |
|---|---|---|
Deal size €2M-€20M | Diligence cost flat across deal sizes; small deals don't pay back the overhead | Below fund ticket-size threshold; allocation strategy concentrates in larger positions |
Equity ratio 20-40% | Higher than standard SME credit profile; pushes LTV outside comfort | Lower than PE control-position requirements |
Residential / mixed-use / value-add asset | Outside LTV comfort for certain collateral types; local-market specialization gap | Not core for institutional mandates (which concentrate in prime commercial and large residential portfolios) |
Standard property mortgage as collateral | Acceptable but Basel capital weighting punishes returns | Insufficient leverage for institutional return targets |
Holding period 2-7 years | Too long for bridge debt; awkward against standard term-sheet conventions | Too short for closed-end PE fund lifecycle |
Read across both tables: the deals in the gap are not bad deals. They are deals whose profile fits neither path's economics.
ONINO's position - and what it does not solve
ONINO is a software provider for issuers in exactly this band. The platform covers eWpG electronic securities through pre-integrated licensed partners, including a BaFin-authorised registrar, with ERC-3643 (T-REX) as the on-chain compliance standard and integrated KYC/AML at onboarding. A white-label layer lets asset managers, banks, and structuring consultants deliver the platform under their own brand. Live in 7+ jurisdictions, with more than EUR 55M tokenized on the infrastructure.
What this does not solve, stated plainly:
Secondary market depth is still developing. Tokenized securities can transfer on-chain under a registered structure, but liquidity at any specific moment depends on counterparty availability. Issuers should not promise investors easy exit; they should structure expectations around the holding period.
Investor risk education is the issuer's responsibility. Lower minimums open the asset class to investors who have not previously held real estate. Under regulated structures, the issuer (or platform operator) is responsible for the suitability and disclosure framework - not the technology layer. The choice between a subordinated loan and a tokenized bond changes this picture too; see our side by side comparison of the two instruments.
Digital securities are not faster bank credit. If a deal genuinely fits standard bank lending and the issuer has the relationship to access it, that is usually still the path of least resistance. The argument here is for deals that the bank path has structurally excluded.
The structural exit exists, and it works - but it is a different operating model, not a free lunch.
Book a structuring call for your real estate deal
If you're sitting on a €2M-€20M real estate deal that has stalled at credit committee or screened out of institutional funds, the right next step is not another bank conversation. It's a 30-minute structuring call with the ONINO team to map your deal against EU exemption frameworks (Prospectus Regulation, ECSPR, eWpG) and evaluate whether a multi-investor digital securities raise fits your timeline, return profile, and investor base.
What you walk away with: a concrete view of which regulatory pathway fits your deal, what the setup looks like (platform setup within one week; the first offering's go-live depends on structuring and partner onboarding), and a realistic estimate of investor reach at €500-€5,000 tickets. No pitch deck, no marketing material - a working structuring conversation, run by the team behind ONINO's issuance infrastructure, live in 7+ jurisdictions.
FAQ
What is the EU prospectus threshold for real estate securities?
The EU Prospectus Regulation allows member states to set a national exemption ceiling for small public offers - up to EUR 12 million per issuer over 12 months as the EU default since the Listing Act, applied in Germany since 5 June 2026; some member states set a lower national ceiling. Below the national threshold, an issuer can offer securities to the public without producing a full EU prospectus, though a securities information sheet (Wertpapier-Informationsblatt under §4 WpPG in Germany) is typically still required. The ECSPR regime adds a separate cross-border passport for raises up to €5M per project owner over 12 months via licensed crowdfunding service providers. Real estate securities can fit inside any of these depending on structure.
Can a mid-sized real estate developer issue digital securities without a bank?
Yes - and this is one of the structural features of the digital securities path. Under eWpG in Germany, an issuer can issue electronic securities directly, with a BaFin-authorised registrar maintaining the register. No bank is required as issuer, paying agent, or distribution party. Without a bank as paying agent, the withholding of German capital gains tax falls on the registrar or, if no registrar is designated, on the issuer itself, so allocate that function in the terms. The issuer may still choose to work with a bank for specific services (paying agent function, escrow, distribution support), but the structural ability to issue is not bank-dependent. ECSPR-based raises through licensed crowdfunding platforms similarly do not require bank involvement.
What investor minimum is typical for tokenized real estate in Germany?
Digital issuance makes small tickets economical to administer; issuers commonly set minimums in the low thousands, and the minimum remains the issuer's decision. That compares with €100,000+ for traditional direct real estate co-investment and roughly €10,000 for traditional real estate funds. The lower minimum is a structural function of how digital securities infrastructure handles per-investor operational cost - automated KYC, on-chain registry, automated distributions - rather than a marketing choice. Issuers can still set higher minimums where the deal structure or investor type makes that appropriate.
General information only, accurate at the date shown. Not legal, tax or investment advice. Confirm your own position with qualified counsel.
Want to learn more how this can be applied to your business?
Read related Articles
Why can't mid-sized European real estate get funded? A 250-issuer cohort analysis of the financing gap and the digital securities path out