Tutorials
Commodity Tokenization: How to Issue Tokenized Commodities in the EU (2026 Guide)
Commodity tokenization for EU issuers: which commodities actually tokenize, which regime applies to your token, and the five steps from custody agreement to secondary market.
Kristina Stark
Growth Manager
last updated on
Kristina Stark
Growth Manager
Share
Contact Us
ONINO provides infrastructure for digital & tokenized financing across the EU and Switzerland.
On this page
Quick Takeaway
Tokenized commodities are worth about US$5.5bn and more than nine tenths of that is gold, so every other commodity is close to open ground. Precious metals are the only category with a working issuance template: bar in an LBMA vault, legal wrapper, on-chain register, redemption right. Industrial metals depend on a warehouse receipt that is not yet digitised in the EU, energy trades as a registry certificate rather than a deliverable, and agricultural commodities break the 1:1 model because physical redemption is impractical. In the EU an issuer lands in one of three regimes: a MiCA asset-referenced token, a security under national law such as a German bearer bond, or a crypto security under the eWpG with a BaFin-authorised registrar. Four variables decide which: custody jurisdiction, redemption model, target investor base, and regulatory perimeter.
Tokenized commodities are worth about US$5.5bn, and more than nine tenths of that is gold. Gold has already settled whether tokenizing a physical asset survives contact with EU rules, which leaves every other commodity, copper, coffee, crude, power, close to open ground.
That gap is the reason this guide exists. The open question for anyone who produces, stores or trades a physical commodity is narrower than whether the mechanics work: what would it take to issue your commodity as a token in the EU, and does your commodity behave enough like gold for the same template to hold?
This guide answers that in five parts: what commodity tokenization is, which commodity types tokenize cleanly and which do not, the five steps of an EU issuance, the regime your token will fall under, and the cases where tokenizing is the wrong answer. It is written for issuers, not for investors deciding what to buy.
What is commodity tokenization?
Commodity tokenization is the practice of representing a physical commodity as a transferable digital token, where each token carries a defined claim on a defined quantity of the underlying good. It is the same mechanic used for tokenizing real-world assets such as property or debt, pointed at something you can weigh.
Every tokenized commodity programme, in any category, is built from the same four parts. A custody arrangement puts the physical good somewhere accountable and produces evidence that it is there. A legal wrapper turns the claim into an instrument that can be sold and transferred under EU law. An on-chain register records who holds which units and enforces the transfer rules in the contract itself. A redemption mechanism defines how a holder gets out, whether by physical delivery, cash settlement, or secondary-market sale only.
Those four parts are also the four places a commodity programme fails, and each of them carries a precise meaning in an offering document that our glossary of tokenization terms sets out. The gold market solved all four years ago, which is why gold is 93% of the category and why the rest of this guide is mostly about whether your commodity can solve them too.
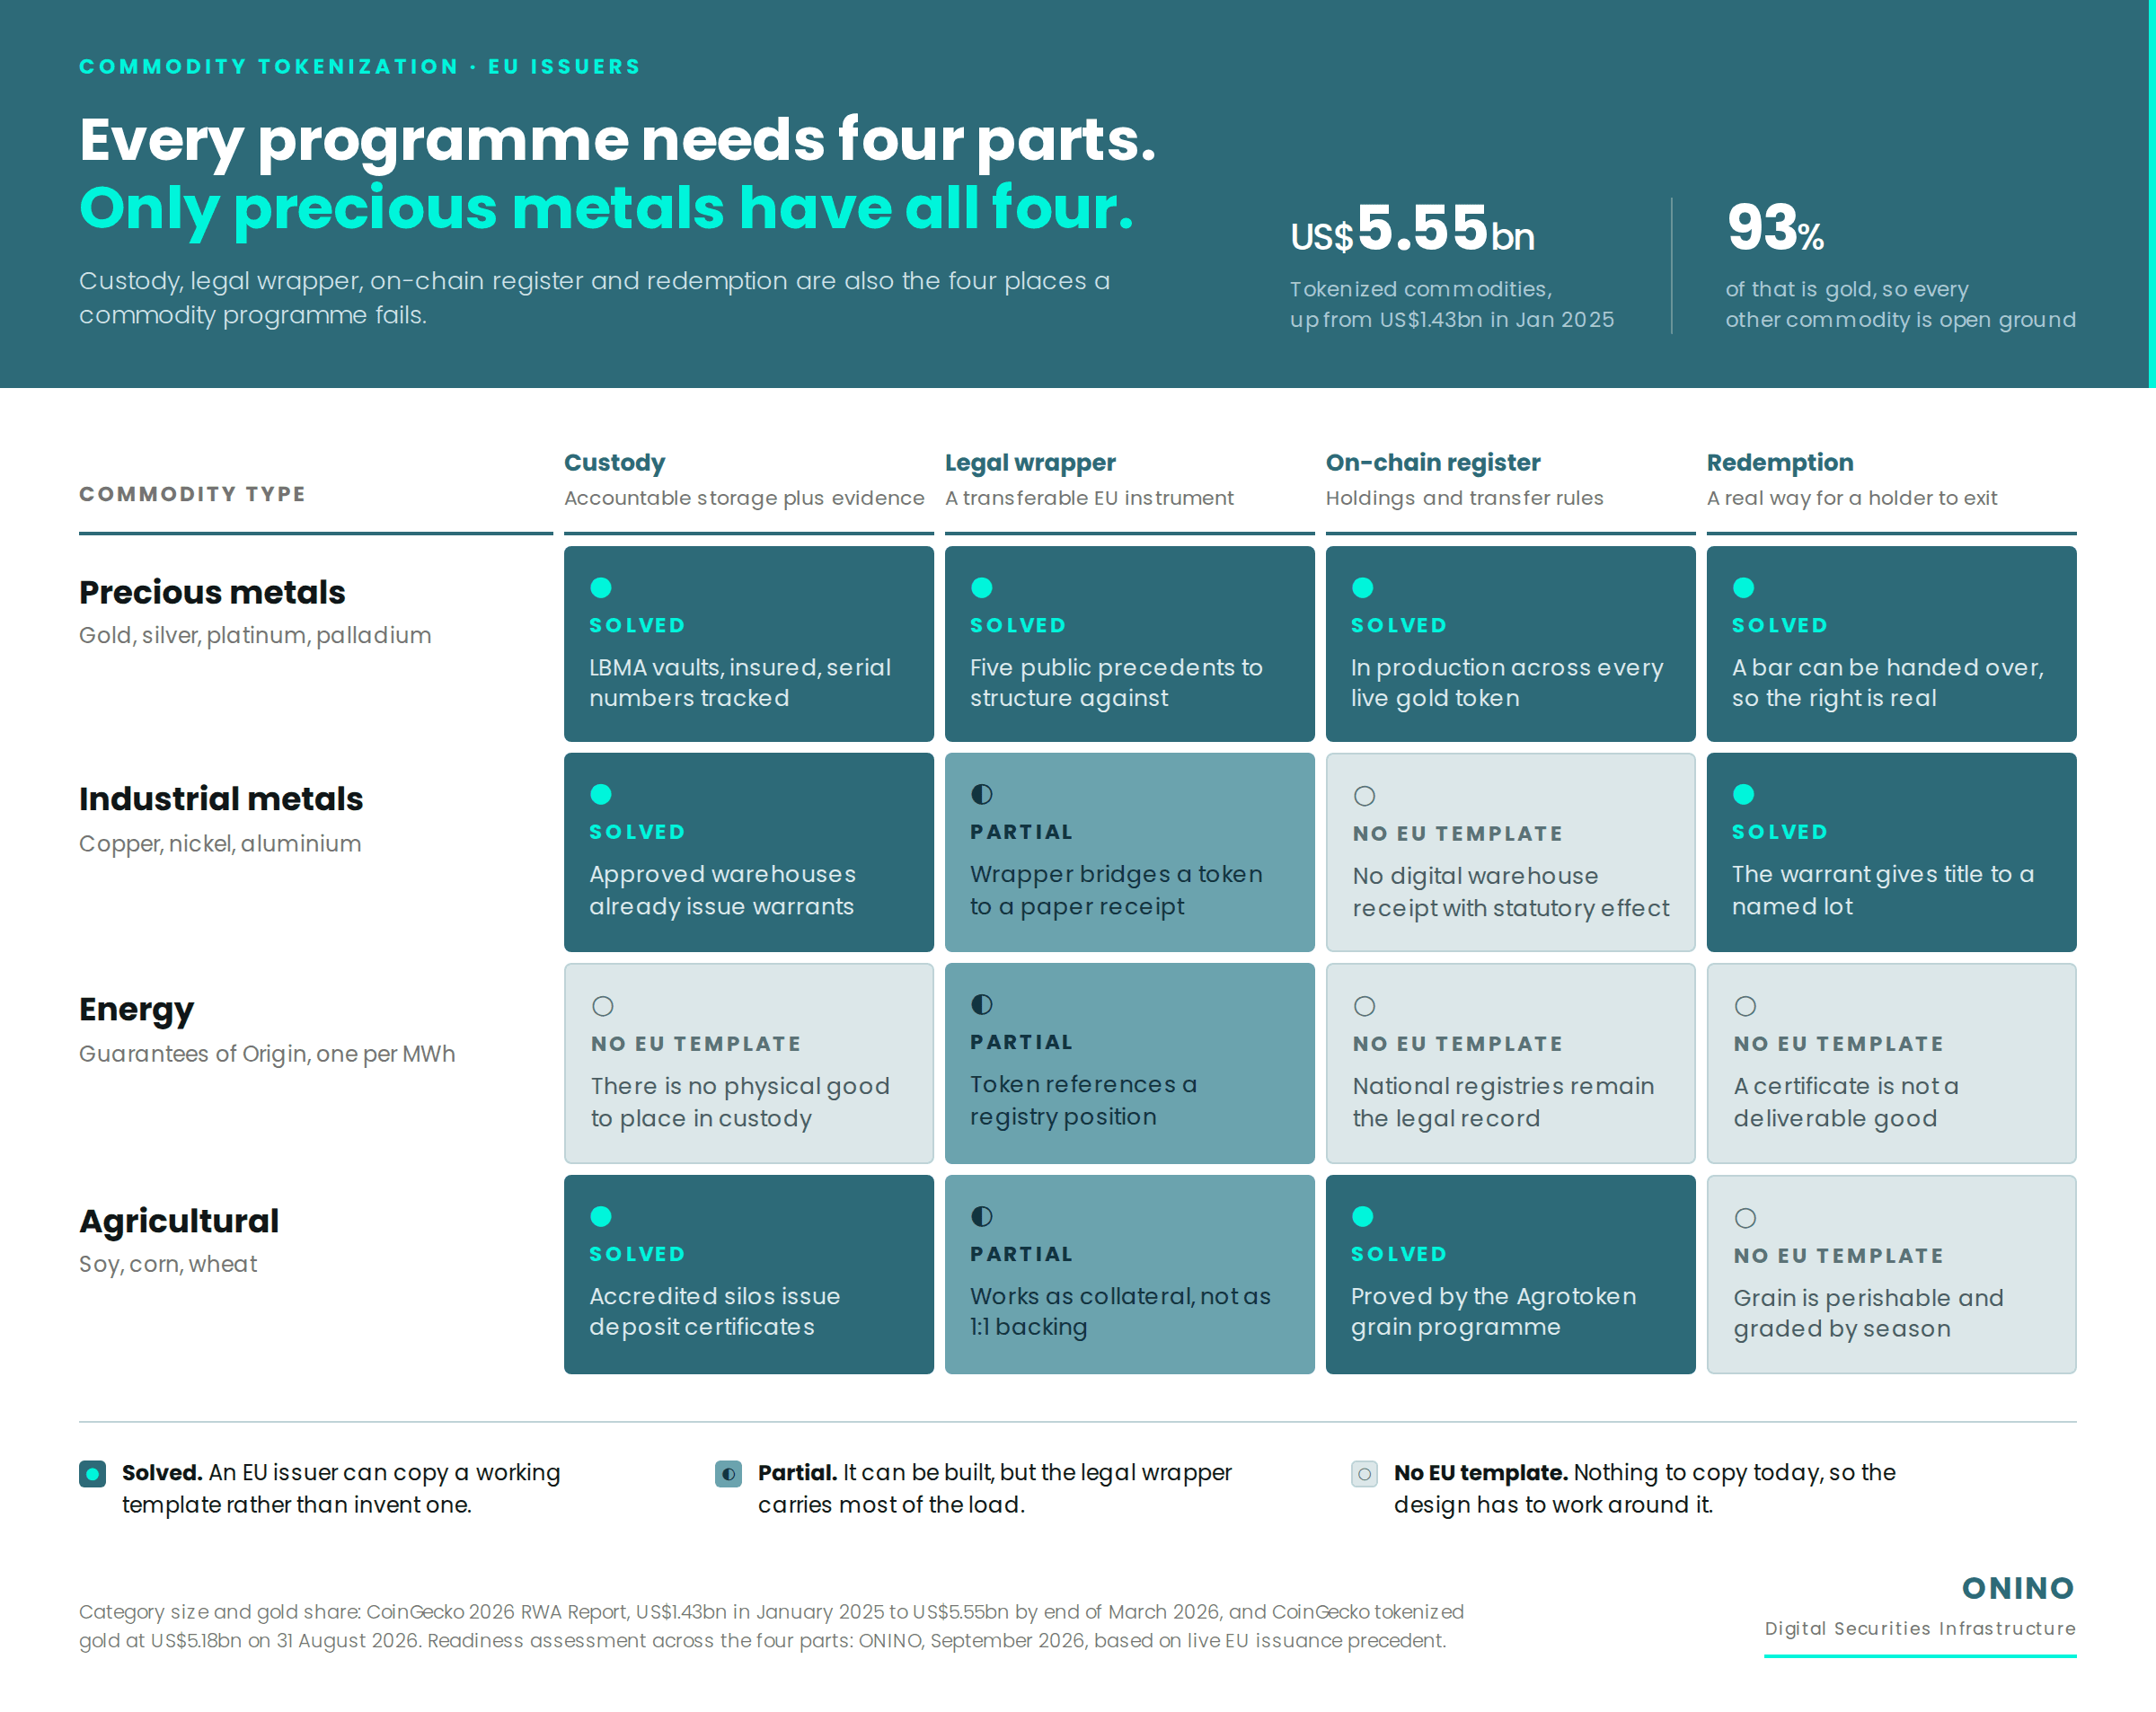
As shown in the graphic, the category is worth US$5.55bn, up from US$1.43bn in January 2025, and 93% of that total is gold. Precious metals are the only type that solves all four parts, which is why the other three are still open.
Precious metals: the only category with a working template
Precious metals are the only commodity type with a template an issuer can copy rather than invent. CoinGecko put the tokenized gold category at US$5.18bn on 31 August 2026, against a whole tokenized commodities category that CoinGecko's 2026 RWA Report tracked from US$1.43bn in January 2025 to US$5.55bn by the end of March 2026. That makes the working precedent and the market almost the same thing: if you are structuring a metals offering, you are structuring against gold whether your metal is gold or not.
The template works because metals answer all four parts cleanly. A troy ounce of London Good Delivery gold is fungible and standardised, vaults accredited by the London Bullion Market Association (LBMA) already exist with insurance and serial-number tracking, the spot price is continuously published so the token can be valued at any moment, and a bar can physically be handed over, so redemption is a real right rather than a promise.
For an issuer, the five established gold tokens are not products to choose between. They are five decisions already made in public, and the useful way to read them is as a decision table.
Precedent | Custody jurisdiction | Denomination | Redemption model | Regulatory perimeter |
|---|---|---|---|---|
Paxos Gold (PAXG) | London, LBMA vaults | 1 fine troy ounce | Physical delivery at wholesale size, or cash | US state regulator (NYDFS), not an EU route |
Tether Gold (XAUT) | Switzerland | 1 fine troy ounce | Physical delivery at wholesale size | Non-EU issuer, higher counterparty scrutiny |
VNX Gold (VNXAU) | Liechtenstein | 1 gram | Cash and physical, per terms | Liechtenstein TVTG, the closest thing to a MiCA-aligned EU route |
Digix Gold (DGX) | Singapore | 1 gram | Physical delivery from small size | Non-EU, reference implementation for gram denomination |
Cache Gold, Comtech Gold, DGLD | Singapore, UAE, Hong Kong | Gram-based | Varies | Niche regimes, including Shariah-compliant structuring |
Read down the last column and the pattern is uncomfortable: only one of these precedents was built inside the EU. An EU issuer copying PAXG's structure is copying a US-supervised instrument, which is why the regime section below matters more here than the technology does.
Silver, platinum and palladium inherit the template with two adjustments. Silver carries roughly the same compliance path but more storage volume per unit of value, so storage economics bite earlier. Platinum group metals share the fungibility and the mature custody infrastructure but sit in far thinner liquidity pools, which changes what an issuer can honestly promise about secondary trading. Anyone building on that promise should read how secondary markets actually form before writing a liquidity claim into an offering document.
Industrial metals: the warehouse receipt is the asset
For industrial metals the token does not represent the metal, it represents the warehouse receipt, and that changes what an issuer is actually structuring. Copper, nickel and aluminium move through the market as warrants: a document issued by an approved warehouse that gives its holder title to a specific lot in a specific shed. The metal itself rarely moves.
China has already digitised that document at scale, and the figures show how large the category can be once the receipt is on-chain. The National Commodity Warehouse Receipt Registration Center launched a blockchain warehouse receipt platform, Cangdeng Chain, with its first digital transactions in Shanghai reported on 11 July 2026, and had registered more than 277,000 tonnes of commodities by May 2026, starting with nickel held by Zhongxin Global Trading and copper owned by Shanghai Wurui Metal Group. Singapore's Ministry of Trade and Industry has been developing a comparable digital warehouse receipt and metal warrant financing framework.
The EU has no equivalent, and that absence is the finding rather than a footnote. An EU issuer tokenizing industrial metal is issuing a claim on a paper receipt whose transfer is still governed by warehouse rules and national property law, not by a digital register with statutory effect. The practical consequence: the legal wrapper has to do far more work than in a gold programme, because it is bridging a token to a document rather than to a bar.
Energy: the certificate is already the instrument
Energy commodities invert the problem, because the tradeable thing is a certificate rather than a deliverable. Renewable electricity is sold with Guarantees of Origin, one certificate per megawatt hour, issued and cancelled inside national registries that operate under the European Energy Certificate System coordinated by the Association of Issuing Bodies. The certificate is what changes hands, and the registry entry is what makes it valid.
That creates a specific structuring question for an issuer: the registry, not the token, is the legal record. A token can carry economic exposure to a Guarantee of Origin or to the revenue from an offtake contract, but it cannot yet replace the registry entry that gives the certificate its legal effect, so the honest design is a token that references a registry position rather than one that claims to be it. Most live EU work in this category is therefore structured as project or revenue exposure, which is closer to a renewable energy financing round than to a metals programme.
Agricultural commodities: why 1:1 backing breaks
Agricultural commodities break the 1:1 backing model, because grain is perishable, graded, and impractical to hand back one unit at a time. Wheat is not fungible the way an ounce of gold is: it is fungible only within a grade, at a moisture level, in a specific silo, in a specific season.
Agrotoken in Argentina is the clearest precedent, and it works precisely because it did not copy the gold model. It issues grain-backed tokens against deposit certificates for soy, corn and wheat held in accredited silos, and the use case that took hold was collateral rather than investment: Banco Santander launched loans to farmers secured on tokenized wheat and corn, letting a producer borrow against grain in storage instead of selling it at harvest prices.
For an EU issuer, the lesson is to stop asking how to back a token 1:1 with a crop and start asking what the token is for. Where the answer is investor exposure, a fund or revenue-sharing structure carries it better than direct backing. Where the answer is working capital, the token is collateral infrastructure and the counterparty is a lender rather than an investor, which puts the design far closer to tokenizing invoices and receivables than to anything in the metals playbook.
How to structure a tokenized commodity offering in the EU
Across all four categories the issuance sequence is the same five steps, and the order matters because each step constrains the next.
Step 1, secure the physical asset and the evidence. Sign with a custodian or warehouse operator that can produce third-party evidence of what it holds. For metals this means an LBMA-accredited vault with serial-number tracking; for grain, an accredited silo with deposit certificates. The custody agreement has to define storage location, insurance cover, audit frequency and the redemption process before the legal wrapper is drafted, because the wrapper describes what the agreement actually permits.
Step 2, define the token structure. Four parameters: denomination, legal instrument, redemption rights, and fee structure. Denomination is a distribution decision as much as a technical one, as Digix showed by moving from ounces to grams to get below the per-ounce entry threshold.
Decision | Options | What it drives |
|---|---|---|
Denomination | 1 token = 1 gram, 1 troy ounce, 1 tonne, 1 MWh, 1 receipt lot | Minimum ticket, and therefore investor type |
Legal instrument | MiCA asset-referenced token, bearer bond, crypto security under eWpG, participation right | Which supervisor and which disclosure regime |
Redemption rights | Physical delivery, cash settlement, secondary market only | Operational complexity and legal structure |
Fee structure | Storage, management and redemption costs passed to holders | Whether the programme amortises at your issuance volume |
Step 3, set up the compliance infrastructure. Identity and anti-money-laundering checks on every investor with ongoing monitoring, transfer restrictions enforced in the contract itself through a token standard built for restricted transfers such as ERC-3643, a prospectus filing or a documented exemption agreed with the national regulator, and the reporting cadence you will owe afterwards.
Step 4, tokenize and distribute. Mint against the custody record, onboard verified investors through a regulated interface where they can review the data room, run the primary sale, and apply the same transfer rules to any secondary listing. Distribution is done by the issuer or through regulated distribution partners, and this is the step where issuers most often discover that their intended investor base does not match the regime they picked in step 2.
Step 5, run the lifecycle. Proof-of-reserves audits on a stated schedule, a price feed linking token value to the underlying, redemption processing, and regulatory reporting. This is the part that runs for years, and it is the part that decides whether the programme was worth building.
[QUOTE, get Lukas to approve the wording before publish]
"The programmes that work are the ones where custody and the legal wrapper were settled before anyone wrote a line of code," says Lukas Wipf, Co-founder and CPO at ONINO. "Issuers ask us first which chain to use. The question that actually decides the project is who holds the metal and what the holder can demand back."
Which EU regime applies to your commodity token
An EU commodity issuer lands in one of three regimes, and which one is a consequence of the four parameters in step 2 rather than a free choice.
You are in MiCA's asset-referenced token regime if the token references a commodity or a basket of assets. That means holding reserves against the tokens in issue, publishing a white paper, and meeting set governance and capital requirements. The transitional period closed on 1 July 2026, so the grandfathering route that existed when this post was first published is gone and a new programme applies for the licence directly.
You are issuing a security under national law if the token behaves like a conventional financial instrument. In Germany a tokenized commodity note structured as a bearer bond and backed by physical metal sits under BaFin supervision, and needs either a prospectus under the EU Prospectus Regulation or a documented exemption, such as the one available for offerings under €8M. Which of those two routes you are in decides your supervisor and your disclosure obligations, so it is worth settling before a single document is drafted.
You are issuing a crypto security under the eWpG, meaning digital securities under German law, if you want the instrument recorded in a crypto-securities register (Kryptowertpapierregister). That register is maintained by a registrar with BaFin authorisation; the permission sits with that partner, not with the software the issuer runs on. Token custody is a separate licensed activity again, held by a crypto custodian under national rules.
Two further frameworks change the arithmetic for smaller programmes. ECSPR, the EU regulation a crowdfunding platform is licensed under, caps offers at €5M per issuer per 12 months, which is often the cleanest route for a first offering. Outside the EU, Switzerland's DLT Act has supported tokenized commodities under FINMA supervision for years, and Liechtenstein's token law (TVTG) is the legal basis VNX used.
The four-variable issuer test
Before choosing a model or a platform, write down four answers. Vendor conversations get sharper the moment an issuer can give them, because each one eliminates options.
Custody jurisdiction. Where does the physical good sit, and who holds title? London, Zurich, Singapore and Liechtenstein carry different regulatory and insurance profiles, and for non-metals the question becomes which warehouse or silo operator, under which national property law.
Redemption model. Physical delivery, cash settlement, or secondary-market exit only? This single answer drives both the legal structure and most of the operating cost.
Target investor base. EU retail, professional and institutional only, or a mix? Investor type decides whether you are under ECSPR at €5M, a prospectus exemption, or a full prospectus.
Regulatory perimeter. A MiCA asset-referenced token, a security under the EU's securities-markets rulebook (MiFID II), a German crypto security under the eWpG, the Swiss DLT Act, or Liechtenstein's token law. Each carries its own licensing, reporting and capital requirements.
What good proof of reserves looks like
Proof of reserves is where commodity programmes are actually judged, and the attestations vary far more than the marketing suggests. A high-quality attestation involves a large audit firm, monthly or weekly publication, lot-level or serial-number identification, and an on-chain hash committing the report to the token contract. A weak one is quarterly, aggregated, and performed by a firm with no commodity audit history.
The four questions that separate them are the same whether you are appointing your own auditor or integrating someone else's token: who audits, how often, is the report cryptographically committed on-chain, and are individual bars or lots identified. An issuer who cannot answer all four in an offering document is asking investors to take the backing on trust, which is the one thing tokenization was supposed to remove.
The same mechanism carries provenance, which is why it is worth building once and using twice. Audited origin data, mining location, refinery, and certification such as LBMA Responsible Sourcing, can be embedded in token metadata before minting, creating a record that travels with the asset. That matters commercially because regulated institutional investors increasingly hold mandates to allocate only to provenance-verified material, and provenance is one of the few things a token delivers better than an exchange-traded product.
When not to tokenize your commodity business
Three patterns say the operating model is not ready, and all three are cost patterns rather than technology ones.
A single-deal issuer rarely amortises the fixed costs of legal structuring, custody onboarding and compliance infrastructure across one offering. If there is no second and third issuance in the plan, the arithmetic usually does not work.
An issuer with no accredited custody relationship has no proof of reserves to publish, and building that relationship from scratch takes months rather than weeks. This is the constraint that most often decides the timeline of a first metals programme.
A redemption-driven retail audience erodes the cost advantage tokenization is meant to create, because shipping, insurance and repeated verification are expensive per unit. Where most holders will want the physical good rather than exposure to its price, a token is the wrong wrapper.
What changes for commodity issuers in the rest of 2026
Three developments shape the second half of the year, and each one moves a deadline rather than a possibility.
The MiCA transitional period ended on 1 July 2026, so crypto-asset service providers that were operating under national frameworks now need a full MiCA licence. Any commodity token brought to market under a transitional regime has to complete authorisation or wind down.
ESMA's March 2026 review of the EU DLT Pilot Regime is expected to widen the authorised infrastructure for secondary trading of tokenized commodities. As of 2026 only four DLT Pilot authorised infrastructures operate EU-wide: CSD Prague, 21X AG, 360X AG and Securitize Europe. For an issuer, that number is the ceiling on where a commodity token can legally trade in the EU today.
Several EU banks have signalled tokenized commodity notes structured as bearer bonds under BaFin or equivalent supervision, using their existing custody and treasury relationships rather than partnering with crypto-native issuers. That is the competitive development to watch, because it changes who the default counterparty for a commodity programme is. Further out, the EU's new anti-money-laundering package applies from 10 July 2027 and harmonises the investor-checking obligations a commodity programme has to carry, so anyone structuring in 2026 should design for both horizons.
In conclusion
Commodity tokenization is a custody and legal-wrapper problem, not a technology problem. Of the four categories, precious metals are the only one where an EU issuer can copy a working template rather than build one, and even there only a single precedent, VNX under Liechtenstein's TVTG, was built inside the EU. Industrial metals wait on a digital warehouse receipt the EU has not yet created, energy trades as a registry certificate a token can reference but not replace, and agricultural commodities work better as collateral than as 1:1 backed exposure.
The next action is the four-variable test, and it belongs to whoever owns the commodity: custody jurisdiction, redemption model, investor base, regulatory perimeter. Answer those four and the regime chooses itself.
ONINO provides white-label financing infrastructure for commodity issuers and financial intermediaries in the EU, covering issuance, compliance, investor management and lifecycle operations, with the licensed functions running through pre-integrated partners and the offering-level obligations sitting with the issuer. Branded environments go live in under 24 hours, with no internal technical build required.
Keep reading. The four-variable test tells you which regime you are in, but not how the offering itself gets built, filed and sold. For that, read how to launch a security token offering next.
General information only, accurate at the date shown. Not legal, tax or investment advice. Confirm your own position with qualified counsel
Want to learn more how this can be applied to your business?
Read related Articles
Commodity tokenization for EU issuers: which commodities actually tokenize, which regime applies to your token, and the five steps from custody agreement to secondary market.