Tutorials
Fund Tokenization: How an Asset Manager Tokenizes a Fund in the EU
How to tokenize an investment fund in the EU. Step-by-step guide covering UCITS, AIF, tokenized feeder funds, and evergreen structures for asset managers.
Lukas Wipf
CPO & Co-Founder
last updated on
Lukas Wipf
CPO & Co-Founder
Share
Contact Us
ONINO provides infrastructure for digital & tokenized financing across the EU and Switzerland.
On this page
Quick Takeaway
Tokenizing a fund means issuing its units electronically and entering them in a register. Four decisions in a fixed order: vehicle, regime, register, issuance. The first already settles everything, because German fund law allows electronic units only for a contractual fund and the investment limited partnership has no route at all. The second is a negative: a tokenized fund unit is a MiFID II financial instrument, so MiCAR does not apply to it. The third is the one vendor material gets wrong: the register is kept by the depositary or a licensed firm the depositary appoints, never by the management company.
Tokenizing a fund does not change the fund. It changes the form of the unit and the record that decides who owns it. The investment strategy stays, the fee structure stays, the depositary stays. What moves is the register entry, and with it the question of who is legally responsible for making that entry.
Most projects run aground on exactly that question, and they run aground earlier than the teams expect. Very few managers have got past it. Four years after German law made this possible, the whole market comes to a handful of named transactions, and almost all of them are bonds rather than fund units. There is no worn path to copy yet, which cuts both ways: nobody can hand you a template, and nobody has set the standard you will be measured against either.
The question this guide answers, for asset managers and private-markets firms, is therefore a narrow one: how does an asset manager tokenize a fund in a way that survives regulatory review? The answer runs through four decisions in a fixed order, and the first one already determines whether the project is possible at all. Vehicle, regime, register, issuance. Reverse the order and start with the technology, and you are building on a structure the law does not support.
Why funds tokenize at all is a different question, answered elsewhere: tokenized funds as the next evolution in asset management covers the case for doing it. This guide covers the doing.
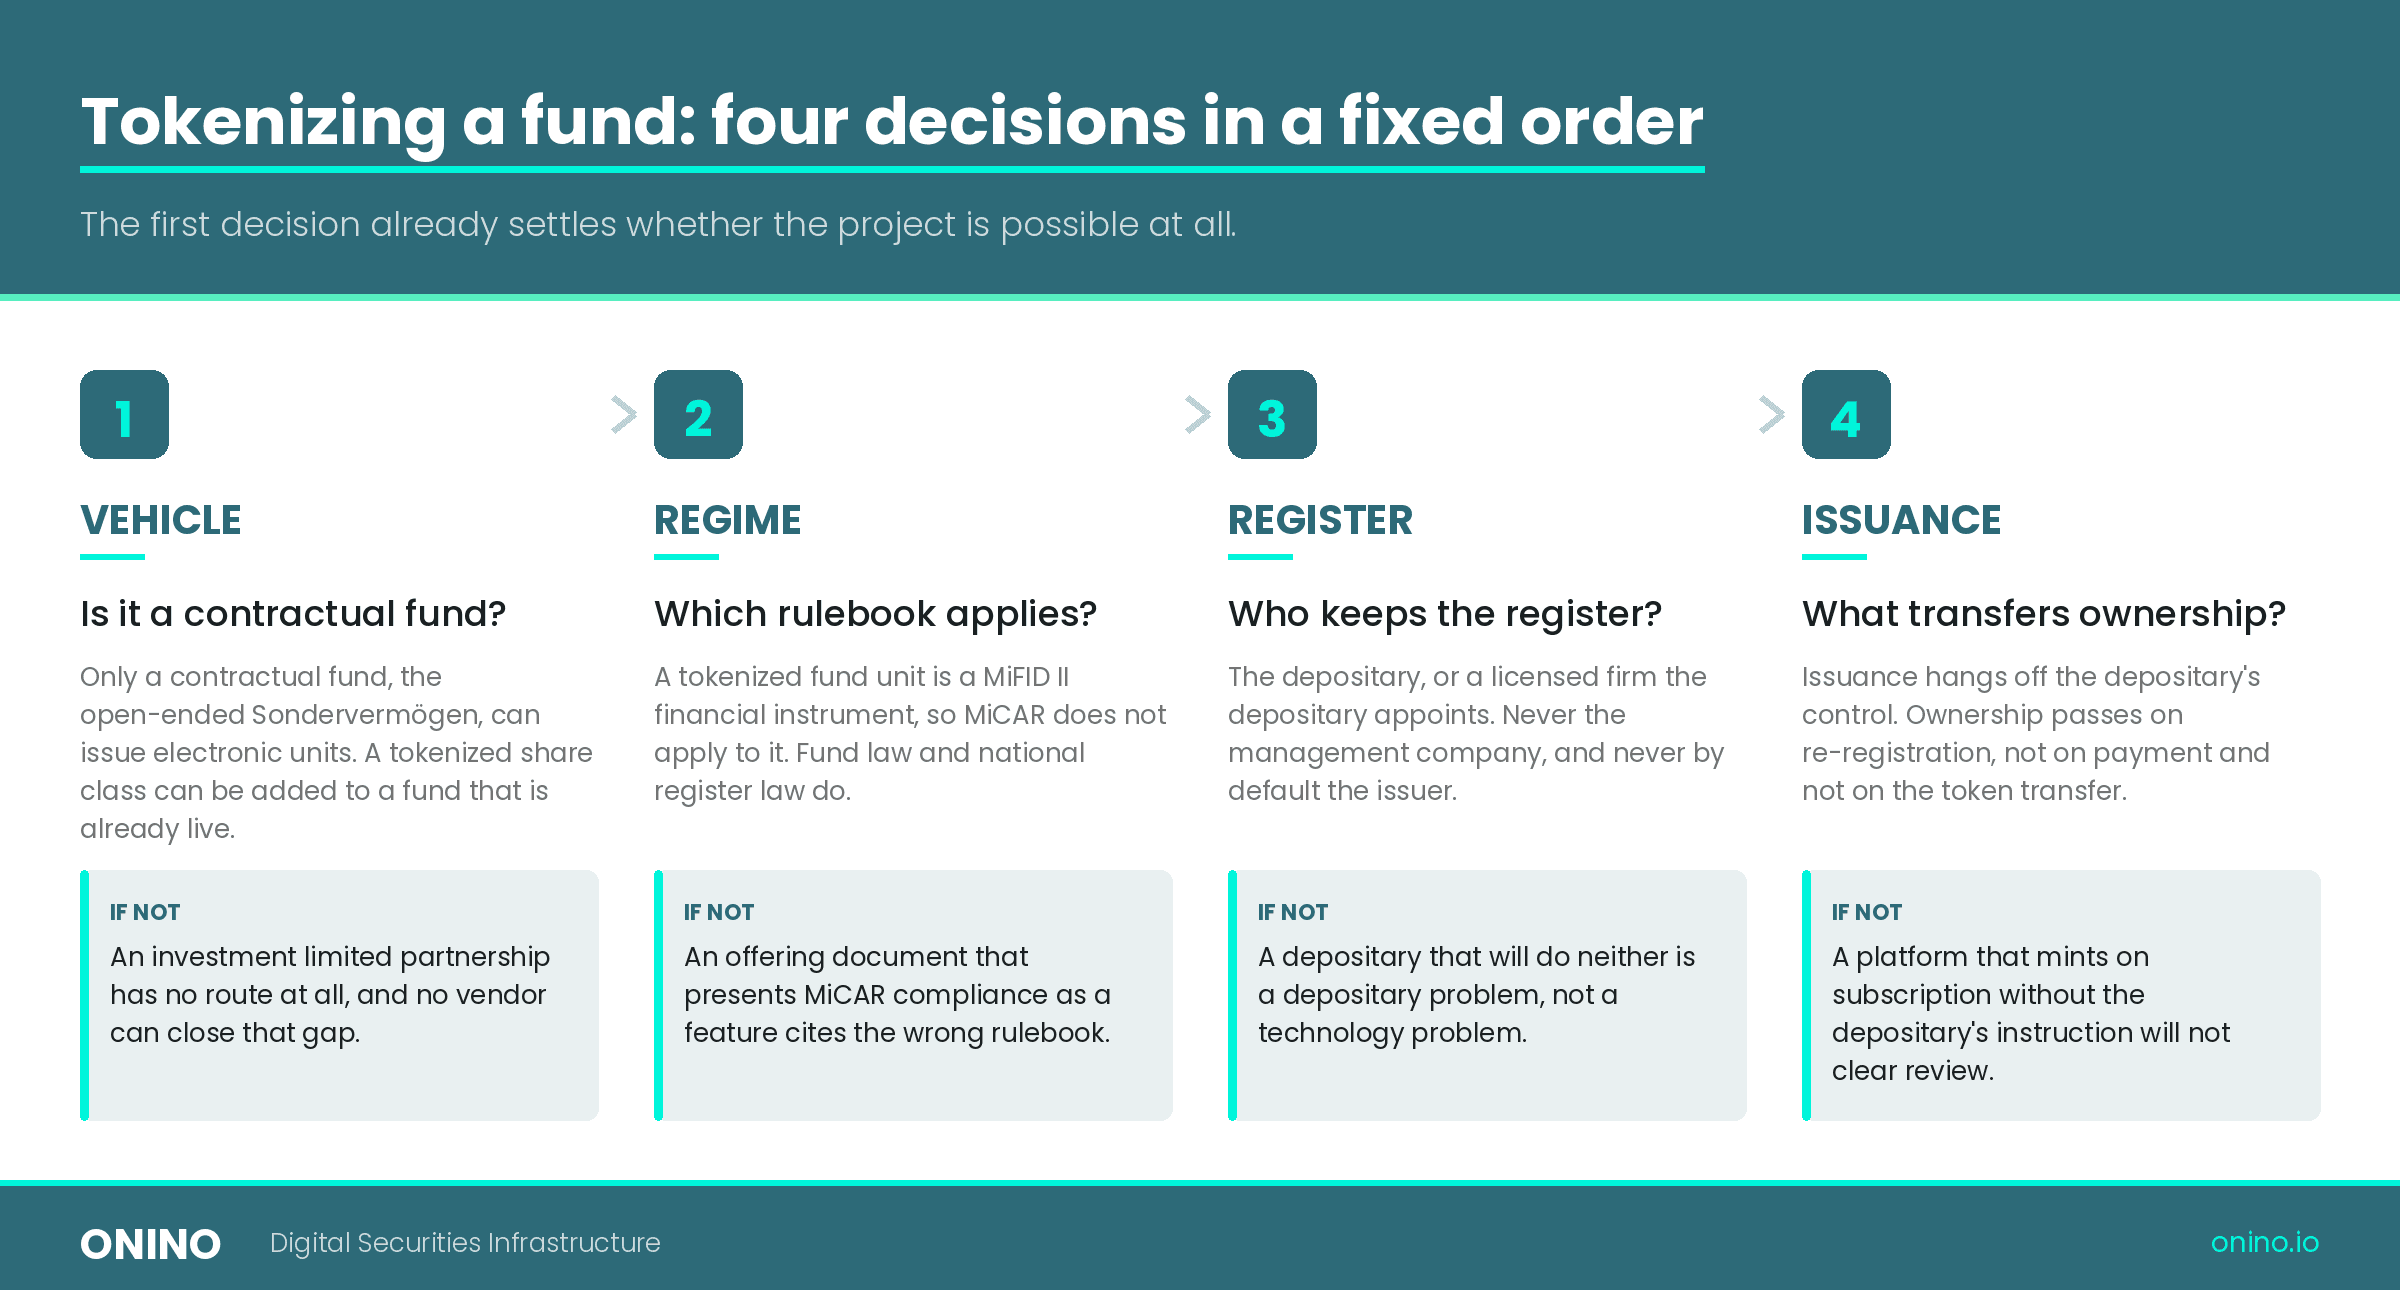
As shown in the graphic, the four decisions run in one direction only: vehicle, then regime, then register, then issuance. Each has a failure state underneath it, and the first one decides whether there is a project at all.
What actually becomes digital when a fund is tokenized
The fund's assets are not tokenized. The unit is. A fund unit is the record of the claim an investor holds against the fund, and traditionally that claim sits in a certificate, in practice a single global certificate deposited with a central securities depository. In an electronic unit, a register entry takes the certificate's place.
German law treats that register entry as an object in its own right, the same legal category as the paper certificate it replaces. That sounds like a lawyer's point and it is the most practical fact in this guide. It means the entry can be owned and passed on exactly as the certificate could, and that good-faith acquisition works the same way. The register is not a copy of the ownership record. It is the ownership record.
From that follows the division of labour that structures the rest of this guide. The register carries the ownership position, the software organises the process around it. Keeping those two apart is the real work. Anyone who collapses them into a single vendor has created a licensing requirement without noticing. Whether you are allowed to attempt either one, though, is settled before both, by the legal form of the fund itself.
Step 1: The vehicle decides whether this is possible at all
The first decision is the hardest, because not every fund form can be tokenized, and the constraint is structural rather than technical. In Germany, the Investment Code permits electronic units only for a contractual fund, the open-ended pooled vehicle known as a Sondervermögen. It does not extend that route to the investment corporation or to the investment limited partnership.
For an open-ended retail or special fund structured as a contractual fund, the route is fully built. Under the Crypto Fund Units Ordinance, in place since 2022, units in a contractual fund may be issued "in whole or in part also as crypto fund units". That phrase is the most consequential wording in the whole text, because it reaches individual unit classes: an existing fund can add a tokenized share class alongside its conventional classes without converting the fund as a whole. In budget terms that is the difference between a product extension and a new fund launch.
The closed-ended investment limited partnership has no route. A limited-partnership interest is neither a bearer bond nor a share, so it sits outside the Electronic Securities Act altogether, and the fund-law route does not reach it either. Since German closed-ended private-markets business runs overwhelmingly through partnership structures, this is the largest practical gap in the regime, and no vendor can close it, leaving closed-ended sponsors with a structuring decision rather than a software decision.
Vehicle | The unit is legally | Can it be issued electronically? |
|---|---|---|
Contractual fund (open-ended) | Fund unit | Yes, both centrally registered and as a crypto fund unit |
Investment corporation | Share | Yes, but only as a registered share in a crypto securities register, and not through the fund-law route |
Investment limited partnership | Partnership interest | No |
A second constraint sits right beside the first and is routinely missed. Fund law allows registered units only insofar as they are not issued electronically. An electronic fund unit is therefore necessarily a bearer instrument, the form in which the entitlement travels with the unit rather than with a name on the fund's own list. An investor structure designed around registered units is designed around the wrong form, and that is a fund-documentation problem rather than a platform setting.
Elsewhere in the EU the vehicle question has different answers, and they are worth knowing before choosing a domicile. France has allowed fund units to be recorded in a shared electronic recording device, its version of a distributed-ledger (DLT) register, since 2018, and its financial code names units of collective investment undertakings expressly. Luxembourg only reached unlisted equity and fund units with its fourth blockchain law at the end of 2024, which also created the control agent role. Ireland has no statutory DLT register route at all, which is why the Central Bank of Ireland's March 2026 discussion paper asks what framework should exist rather than describing one that does. For a manager choosing where to domicile a tokenized vehicle, that gap is the sharpest comparison on the table.
Jurisdiction | Can fund units be registered on DLT? | Since | What the token legally is |
|---|---|---|---|
Germany | Yes, for contractual funds only | 2022 | The register itself, kept by the depositary or a licensed firm it appoints |
France | Yes, expressly including fund units | 2018 | The register, at the issuer's election |
Luxembourg | Yes, since unlisted equity and fund units were added | End of 2024 | The register, with a control agent over the issuance account |
Ireland | No statutory route | Not applicable | A mirror of the administrator's register, which remains authoritative |
With the vehicle settled, the next question is which rulebook applies, and most teams expect that to be the hard one.
Step 2: Which rulebook applies, and which one does not apply at all
It is not the hard one, because the most important part of the answer is a negative. A tokenized fund unit is a financial instrument under MiFID II, the EU's securities-markets rulebook, because its instrument list covers units in collective investment undertakings irrespective of their technical form. MiCAR, the EU crypto-asset regulation, then removes anything that already qualifies as a financial instrument from its own scope entirely.
In practice that means one thing: a tokenized fund unit does not fall under MiCAR. No white paper, no crypto-asset service provider licence for the issuer, no notification duties from that regulation. ESMA has confirmed the position in its guidelines on when a crypto-asset counts as a financial instrument, holding expressly that tokenizing a financial instrument does not change its classification. An offering document that presents MiCAR compliance as a feature of a fund unit is citing the wrong rulebook, and a reviewer will notice immediately.
What applies instead is the familiar stack: fund law for the vehicle and its distribution, national register law for the form of the unit, MiFID II for the service provided to the investor.
Investor category then drives the documentation burden, because it decides which approvals you need. A special fund is defined by the fact that only professional and semi-professional investors may acquire its units; everything else is a retail fund. Qualifying an investor as semi-professional takes four conditions together, three of which are documents you can collect and one of which you cannot delegate to a questionnaire: the manager's own assessment of that investor's knowledge and experience. Budget staff time for it.
However, a third layer bites on retail distribution, and it is easy to get backwards. Fund units are excluded from the Prospectus Regulation, but the exclusion is drafted for undertakings other than the closed-end type. It therefore turns on open-ended versus closed-ended, not on retail versus special. Closed-ended vehicles, which is most private-markets structures and most European long-term investment funds (ELTIFs), are not excluded. A closed-ended retail fund can owe a prospectus, the standard pre-investment disclosure for alternative funds and a PRIIPs key information document, the short retail disclosure sheet, all at the same time.
One EU-level constraint catches private-markets managers specifically. The DLT Pilot Regime, the EU sandbox for trading and settling tokenized instruments, admits fund units only where they are units in non-structured UCITS, meaning plain open-ended retail funds, with assets under management below EUR 500 million. Units in alternative investment funds are not eligible. A tokenized alternative fund therefore cannot use the pilot regime at all and runs entirely on national register law, which is why the German route matters more than its market size suggests. National register law is also where the single most misunderstood rule in fund tokenization sits, and it decides who is allowed to keep the record at all.
Step 3: Who keeps the register, and why it is not the asset manager
That rule is where fund tokenization differs from every other kind, and it is where vendor material is most often wrong.
For an ordinary crypto security, the Electronic Securities Act makes the register-keeping entity whoever the issuer names to the holder, and where the issuer names nobody, the issuer itself is the register-keeper by default. That default is a licensing trap. Keeping a crypto securities register is a regulated financial service in Germany and needs a licence from BaFin, the German financial regulator. BaFin's 2023 guidance on what counts as register-keeping names crypto fund units expressly, so nobody can argue the point is unsettled. An issuer that simply never made the choice has walked into a permission requirement it does not hold.
For fund units, that default is switched off. The Crypto Fund Units Ordinance puts register-keeping with the depositary, or with another firm the depositary appoints that holds the crypto securities register licence itself. The management company cannot keep the register, and the issuer cannot fall into the licensing requirement by accident. Where the depositary appoints a third party, it has to remain able to discharge its own custody and control duties over the fund.
That reorders the project. The depositary stops being purely a control function and moves into an active register role, which makes the choice of register-keeper the depositary's decision rather than a procurement decision by the asset manager. A manager whose depositary neither holds the licence itself nor is willing to appoint a licensed provider does not have a technology problem. It has a depositary problem, and the fix is a change of depositary. That question belongs at the start of the project, not in the implementation phase.
"The first question we get asked is almost always about the technology, and it is almost always the wrong first question," says Lukas Wipf, Co-founder and CPO at ONINO. "By the time a manager is choosing software, the vehicle and the depositary have already settled what is possible. Our part starts after those two answers, not before them."
The software an offering runs on has nothing to do with the licence. The crypto securities register is maintained by a BaFin-authorised registrar; the permission sits with that partner, not with ONINO. As a software provider, ONINO covers the technical layer and brings the licensed functions in through pre-integrated partners, so an issuer does not have to source registrar, custodian and payment institution separately. The ONINO platform supports several instrument rails in parallel, and asset tokenization is one of them rather than the only one.
Step 4: Issuance, and what actually transfers ownership
With the register settled, issuance becomes an operational question, and it starts with a rule that has nothing to do with tokenization. German fund law makes the depositary responsible for issuing and redeeming units, permits issuance only against full payment of the issue price, and requires that payment to be booked to a blocked account. Applied to a tokenized class, minting and burning have to hang off the depositary's control rather than off a process run by the management company or a platform operator. A target operating model in which the platform mints on subscription without the depositary's instruction will not clear review.
The genuine product decision comes next. The Electronic Securities Act, which reaches fund units through the Crypto Fund Units Ordinance, sets two registration modes side by side, and the choice between them determines how the unit is distributed and held.
Registration mode | Who appears in the register | What it enables | What it costs |
|---|---|---|---|
Individual registration | The investor | Direct distribution without a securities account; investor data sits with the issuer | No connection to the existing custody chain |
Collective registration | A central securities depository or a custodian | Compatibility with the existing distribution route through securities accounts | The investor stays invisible to the issuer |
Both are permitted, and a mixed holding is allowed as well. However, whether a crypto fund unit can in practice be brought into collective safe custody and settled like a conventional unit is unresolved. The part of the Act written for collective safe custody assumes a central register, while the fund rules assign register-keeping to the depositary, and the two do not meet cleanly. The industry association Bitkom asked for the conflicting provision to be deleted in its March 2026 submission to the statutory review of the Act, for exactly this reason. That is analysis rather than settled law, and a manager planning distribution through securities accounts should get the point resolved legally before solving it technically.
Ownership, finally, passes neither on payment nor on the token transfer. A disposition takes effect only on registration or re-registration, and the holder does not lose ownership until the acquirer has been re-registered. A wallet-to-wallet movement that bypasses the register-keeper moves nothing, so the secondary-transfer flow has to be built around the register-keeper's instruction. How an investor reaches that entry in the first place, from registration through anti-money-laundering checks and suitability to subscription, is a separate sequence with its own legal basis and is the subject of a dedicated guide to investor onboarding. What follows the first allocation, from capital calls and distributions through to redemption, is its own sequence again.
What the regulator decides, and how long each step takes
All four steps run against a supervisory clock, and it is better documented than the market generally assumes. German fund law gives hard deadlines for each procedural step, and every one of them runs from receipt of the complete application, putting the schedule in the applicant's hands rather than the regulator's. That qualifier carries the whole calendar, because completeness, not supervisory speed, is what actually delays a project.
What you are waiting for | How long the regulator has | When it applies to you |
|---|---|---|
Licence for a UCITS management company | 6 months | Only if you are not already an authorised manager |
Licence for an alternative fund management company | 3 months, extendable by up to 3 more | Only if you are not already an authorised manager |
Approval of fund rules (retail fund) | 4 weeks, approval deemed given once the deadline passes | New fund, or a rule change to an existing one |
Marketing notification for a special alternative fund | 20 working days | Before you market to professional investors |
Licence for crypto securities register-keeping | No statutory deadline | Your register-keeper's timeline, not yours |
No supervisory authority publishes a total time to first tokenized issuance, and neither does any industry body. A figure of that kind in a vendor proposal is that vendor's estimate. For an already authorised manager adding a tokenized class to a live fund, only the bottom two rows apply anyway, because the licence and the vehicle already exist. That is precisely why the share-class route is more attractive in practice than launching a new fund. What the calendar does not tell you is how many managers have actually run it.
Where the market actually stands
Very few, and the most useful number in this market is how small it is. The Deka Digital Asset Monitor of 12 February 2026 puts the cumulative volume of all tokenized securities issued in Germany at EUR 1.23 billion, with 71 issuances in the second half of 2025 alone. That EUR 1.23 billion is a running total across every issuer and every instrument type since the regime began, not an annual figure, which is the detail that makes it small rather than large. DekaBank is itself a licensed register-keeper and the survey is not official statistics, so read it as the best available count rather than as an official one. What matters for fund units is what the report does not break out: a split by asset class. Essentially all identifiable issuance is bearer bonds, and fund units are an unquantified remainder.
The fund side has to be read from individual transactions instead. Metzler Asset Management issued Germany's first crypto fund units on 5 September 2023, as a share class not open to public subscription and expressly as a three-month pilot. In October 2023 Union Investment bought units of that class into one of its own multi-asset funds, the first transaction in crypto fund units between two houses. Neither firm has published efficiency figures. Four years after the legal basis was created, this market therefore stands at a handful of nameable transactions, which for an asset manager reads less as a warning than as a window. It also answers the question this guide opened with in a way the regulation alone does not: nobody will review your structure against an established market practice, because there is no established market practice yet, so the procedures can still be written down before a live closing sits on top of them.
The European picture is no larger. In its June 2025 report on the DLT Pilot Regime, ESMA counted exactly three authorised DLT market infrastructures across the whole Union as at 31 May 2025, two of them German. The only one with meaningful equity activity had run six issues totalling EUR 11.9 million, against a regime cap of EUR 6 billion. Capacity is not the constraint, and ESMA's own recommendations point at the sunset clause and the absence of central bank money settlement instead. The practical reading is that national register law, not the pilot regime, is where a tokenized fund actually gets built, and it is also where the remaining uncertainty sits.
What is still open, and what to do next quarter
Four of those uncertainties are legally unresolved, and a project should know them rather than discover them. First, the collective registration point above, and how a crypto fund unit settles through the custody chain. Second, whether a smart contract can trigger re-registration on its own: the law requires an instruction from an identified authorised party as well as an agreement between the parties, which fully automated secondary transfer does not currently satisfy. Third, how far a platform provider may operate around the register before it compromises the depositary's control duty. Fourth, how the electronic form should be disclosed in the prospectus, since the disclosure rules are written for certificates and were never updated for electronic units.
The framework is also moving. The Electronic Securities Act was amended in February 2026, and a formal statutory review drew industry submissions in March 2026. A legal position taken from last year is not a reliable legal position here, and the four questions above belong with counsel before the first issuance rather than in a product brochure.
Ultimately the answer to the opening question reduces to a single order of enquiry, and technology is not the first item in it. An asset manager who wants to start seriously next quarter should establish, in this order: whether the vehicle is a contractual fund, whether a new share class will do instead of a new fund, and whether the depositary is willing either to keep the crypto fund unit register itself or to appoint an authorised register-keeper. Of the three, the depositary question is the one that most often kills a project, because it is the only one the asset manager cannot decide alone. If any of the three answers is no, no software selection solves it. If all three are yes, the rest is execution and the deadlines are in the statute. Background on the instrument form itself sits in the overview of digital securities.
General information only, accurate at the date shown. Not legal, tax or investment advice. Confirm your own position with qualified counsel
Want to learn more how this can be applied to your business?
Read related Articles
How to tokenize an investment fund in the EU. Step-by-step guide covering UCITS, AIF, tokenized feeder funds, and evergreen structures for asset managers.